Eyes on the Market: Risk-Off Ahead of Decisions
Published On 14 September 2026
- Risk-off into a week of decisions. BTC fell 2.96% to $77,257 and total crypto market cap 2.91% to $2.634T. ETH finished flat at $2,505.50. Measured to Sunday's futures close, the Nasdaq lost 1.81% and the S&P 1.26%.
- Oil ran again. Brent gained 8.93%, peaking at $109.80 before reversing on reports Iran would meet Gulf states in Oman over Hormuz shipping. A second consecutive week of large gains as the US-Iran conflict continued.
- Energy driven inflation. August PPI came in at 5.4% y/y, the highest of the year, on a 24.1% monthly jump in diesel. CPI followed at 0.4% m/m with gasoline up 3.9% and accounting for over a third of the entire monthly increase. Annual core eased to 2.4%, the lowest since March 2021, while monthly core ran a tenth hot.
- Hike odds reprice hard. September hike odds went from 57% to 79% on Polymarket and 67% to 86% on FedWatch. Markets now price four hikes by June 2027 to a 4.50% to 4.75% target.
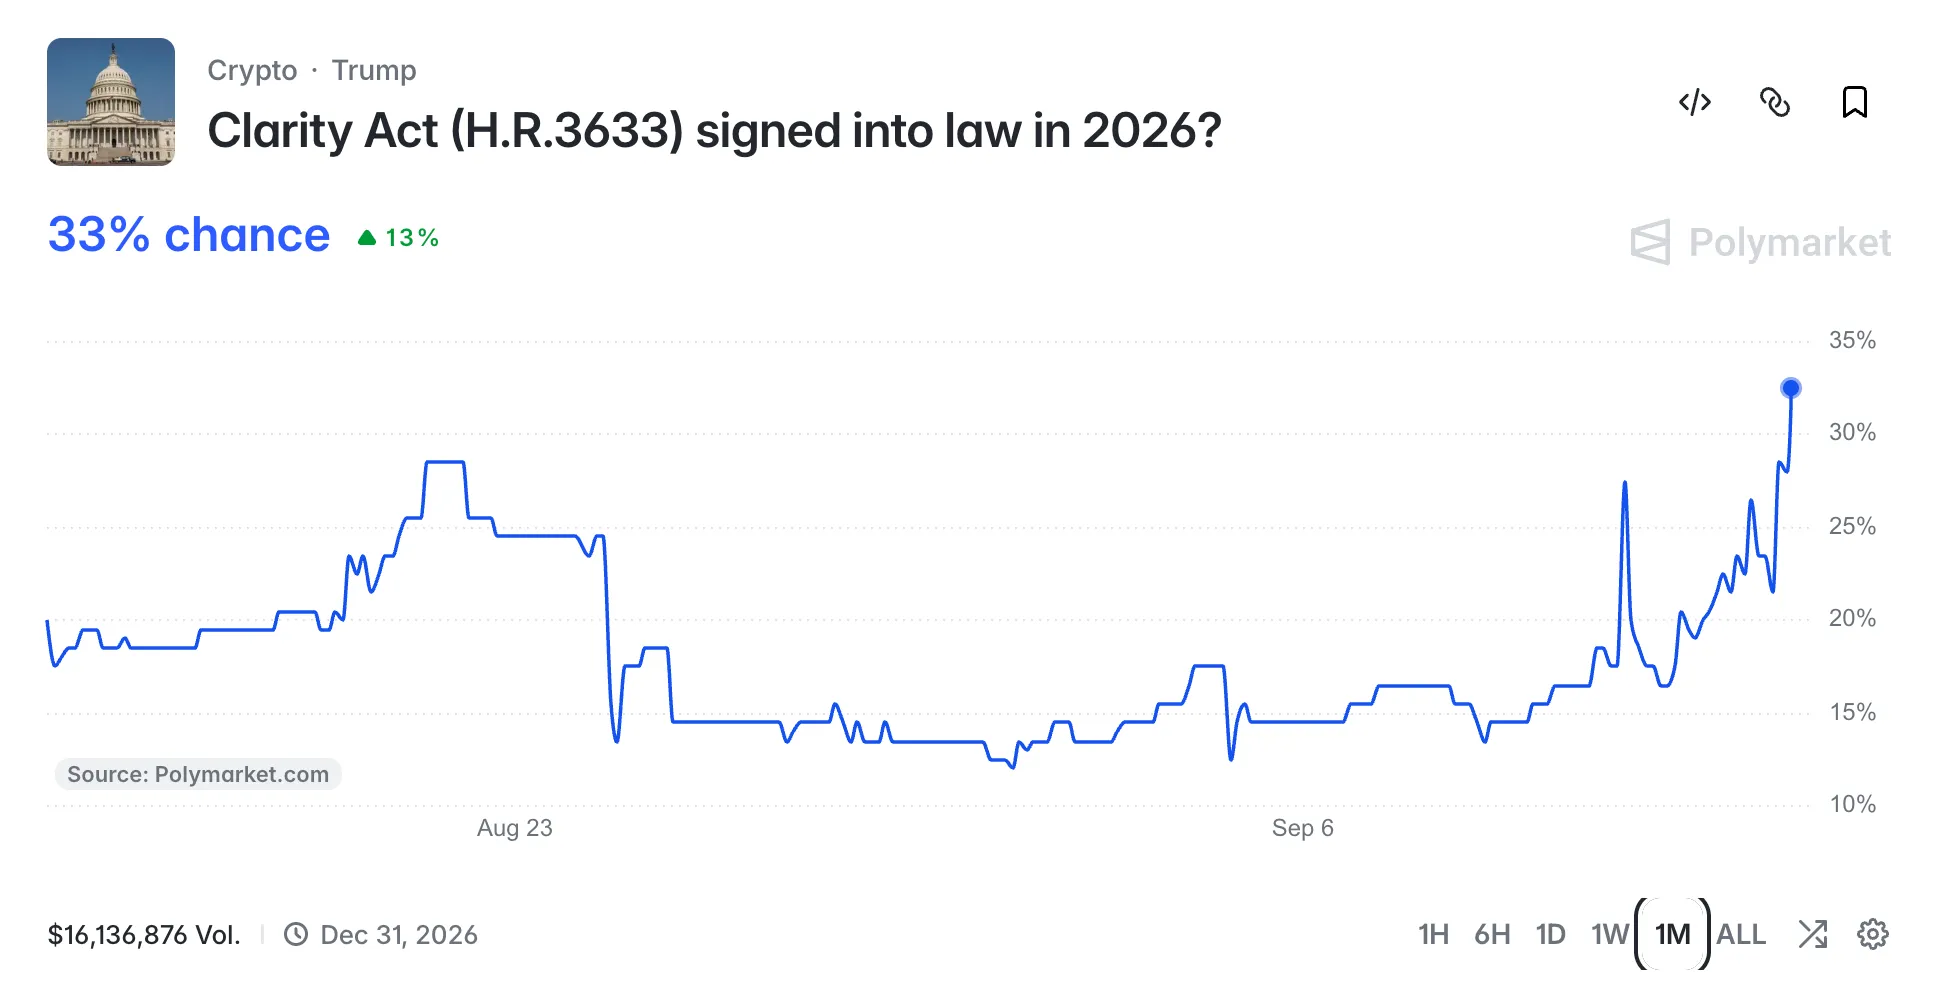
- CLARITY optimism. Senate Republicans released their last, best and final offer late Sunday night with Trump signed on to the ethics language. Odds of passage this year rose 13 points to 33%. Cloture is Tuesday and needs 60 votes.
- ETFs reversed. BTC saw $462.7M of outflows across four sessions with zero inflow days, ending three straight weeks above $1B. ETH took $197.1M and is +$1.06B year to date against BTC's -$1.46B.
De-risking across the board
BTC opened Monday at $79,611 and closed Sunday at $77,257, down 2.96% on the week. Its weakest reading came in Sunday's session at $76,531. Total crypto market cap fell 2.91% to $2.634T. ETH held up better, finishing flat at $2,505.50.
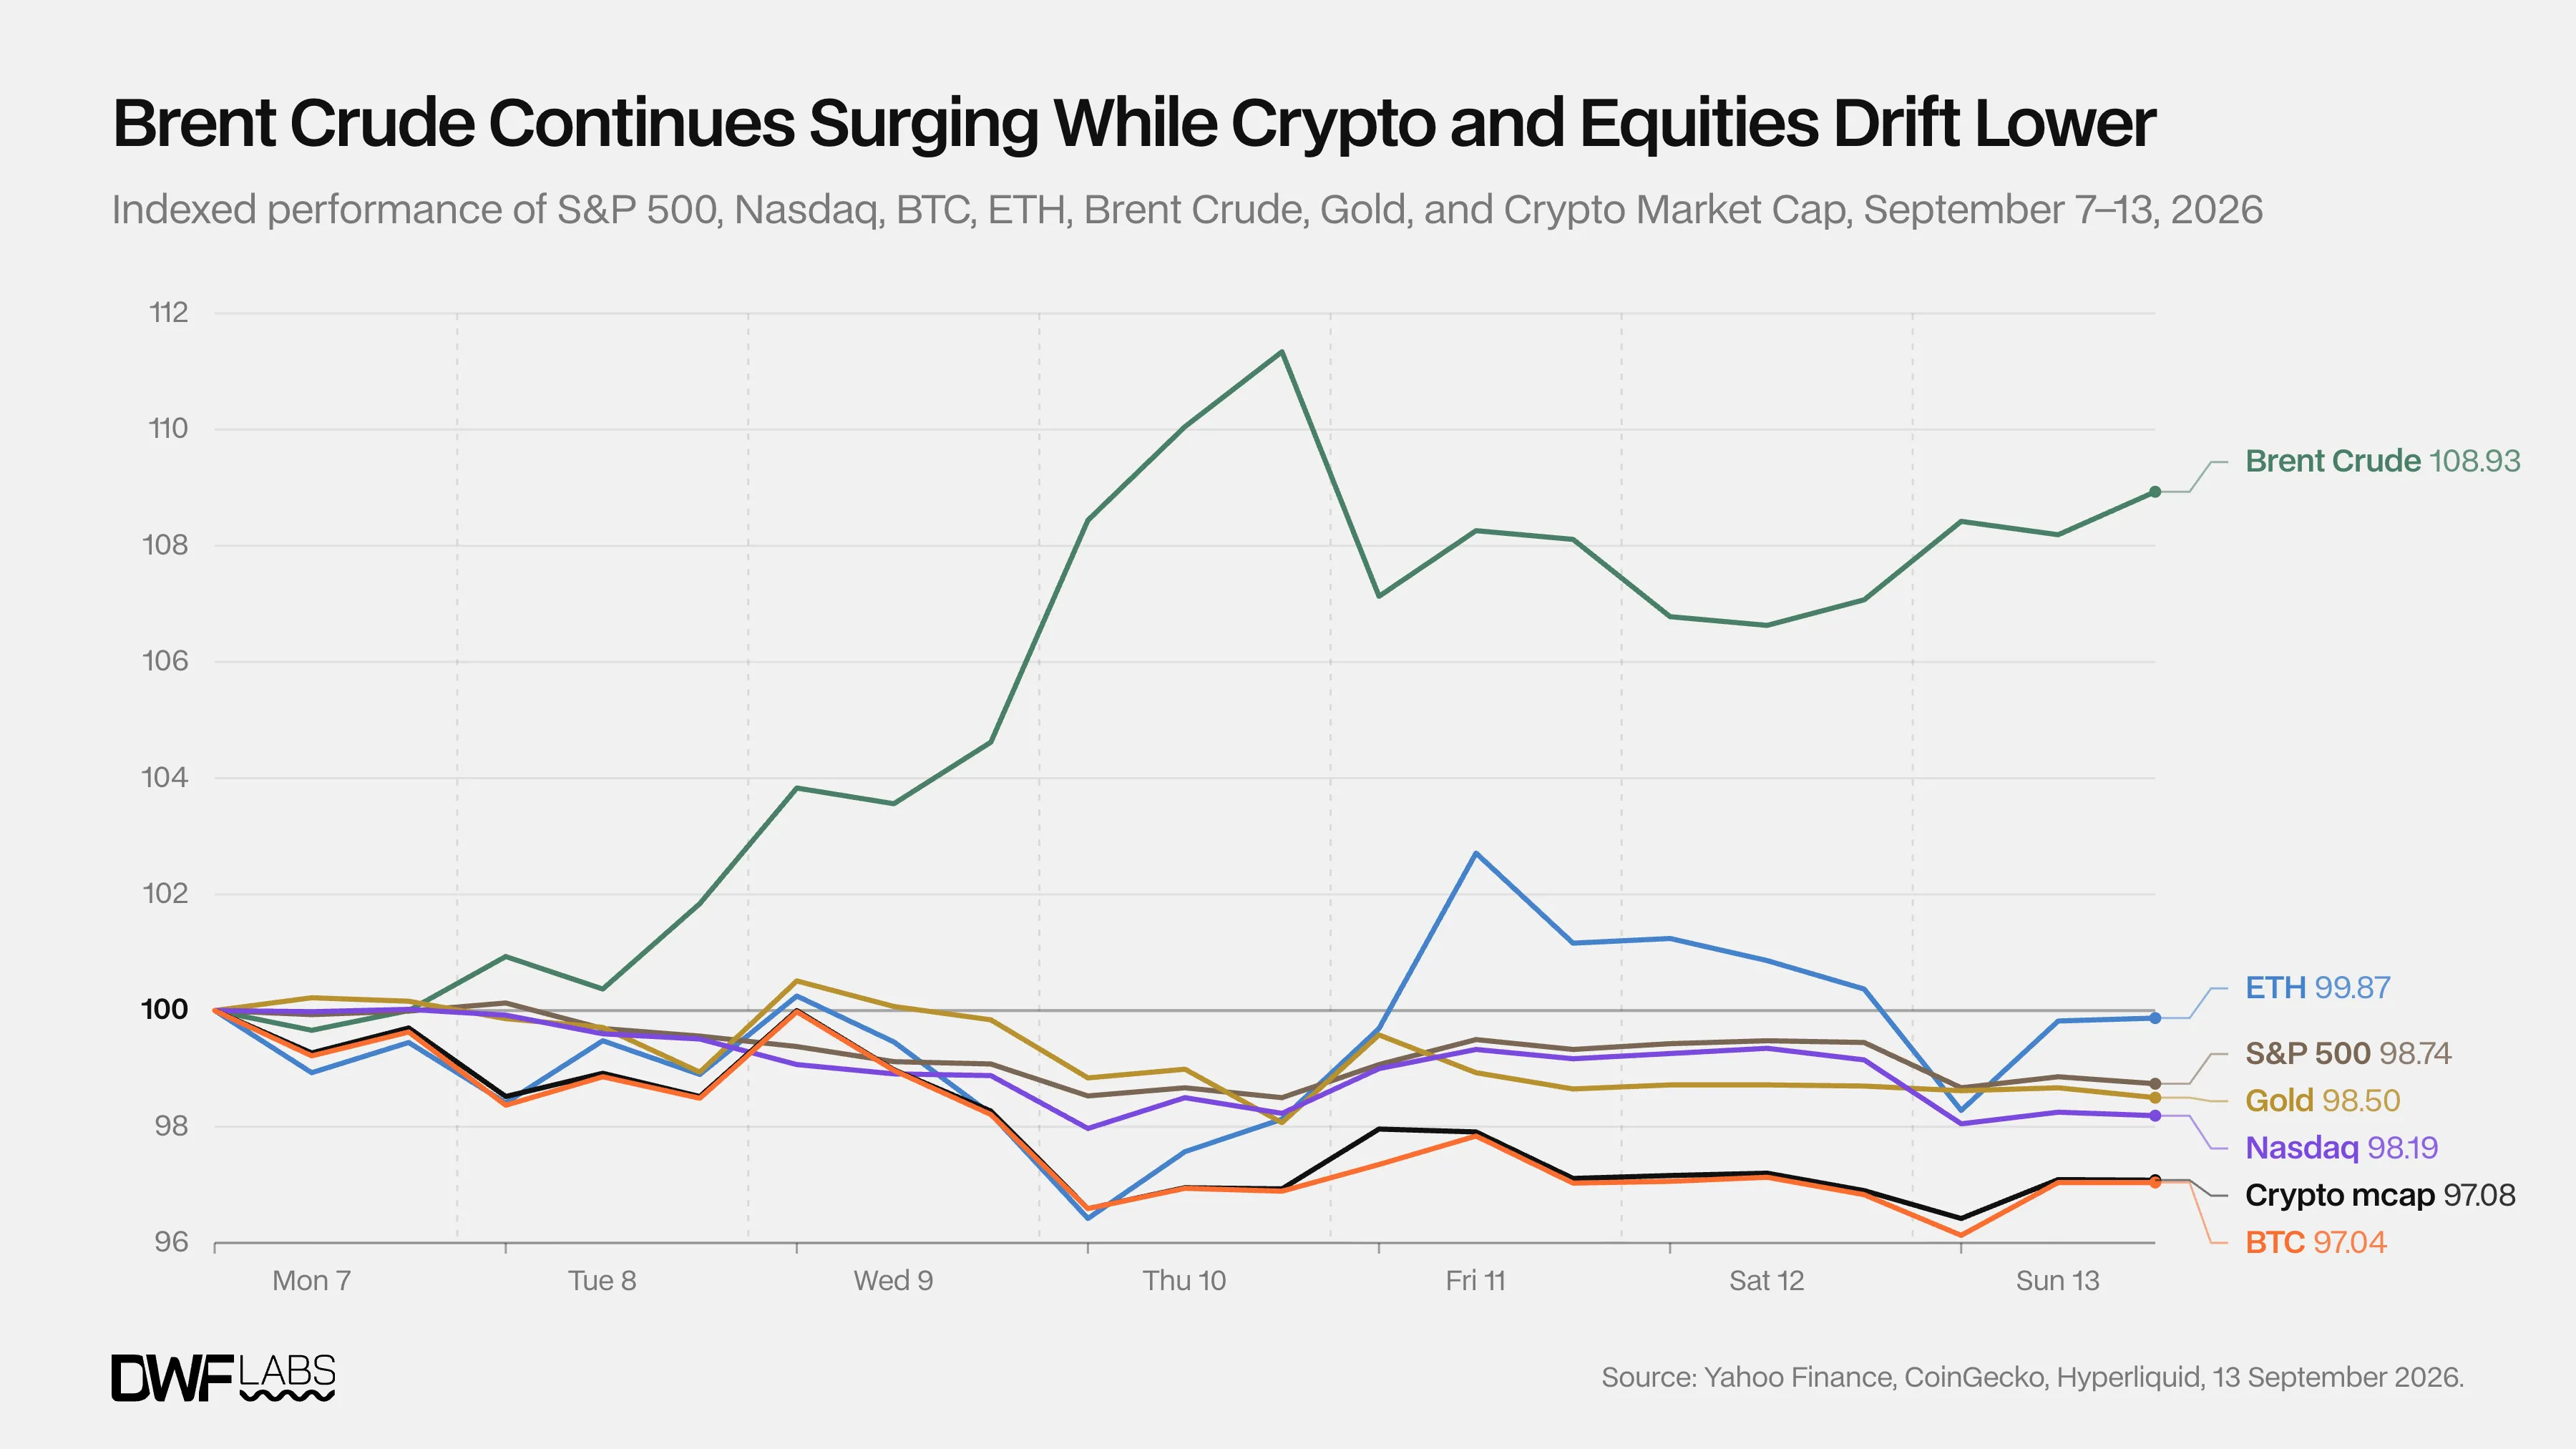
Brent peaked at $109.80 late Thursday and gave it back through Friday, closing at $104.91 after Iranian state media said Tehran would meet Gulf states in Oman on Hormuz shipping. It closed Sunday up 8.93% on the week, a second consecutive week of large gains as the US-Iran conflict continued. Gold fell 1.50% to $4,384.40. Equity futures drifted lower over the weekend after Dario Amodei's Saturday essay arguing that AI labs should deliberately slow the rate at which they improve model capabilities, which Sam Altman and Elon Musk both endorsed within a day. Measured to Sunday's futures close, the Nasdaq ended the week down 1.81% and the S&P down 1.26%, against 0.83% and 0.67% at Friday's cash close.
Events of the Week
Producer Prices Hit First
August PPI landed Thursday at 0.4% m/m and 5.4% y/y, the highest twelve-month reading of the year. Final demand goods rose 1.1%, with over three quarters of that coming from energy. Diesel alone rose 24.1% on the month and accounted for more than a third of the increase in goods prices. Core PPI was the soft part of the report at 0.2% m/m against a 0.3% forecast, and 4.6% y/y. Treasury yields rose, equity futures fell, and September 10 became the worst crypto session of the week on both price and ETF flows.
Mixed CPI Print
August CPI arrived Friday at 0.4% m/m and 3.4% y/y, both in line. Core accelerated to 0.3% m/m from 0.2%, a tenth above forecast. Annual core eased to 2.4% from 2.5%, the lowest reading since March 2021. Underlying inflation is easing year over year while the month-to-month trend is not cleanly cooling.
Gasoline rose 3.9% on the month and 27.4% over the year, accounting for over a third of the entire monthly all-items increase. The broader energy index rose 2.1% on the month and 16.3% on the year.
Hike odds on Polymarket jumped from 57% to 79%, and 67% to 86% on CME’s FedWatch. Markets now price a base case of four hikes by June 2027 to a target rate of 4.50% to 4.75%. Sentiment is still split on whether Warsh follows through on Wednesday. This is one of the most closely watched and least certain FOMC meetings in recent memory.
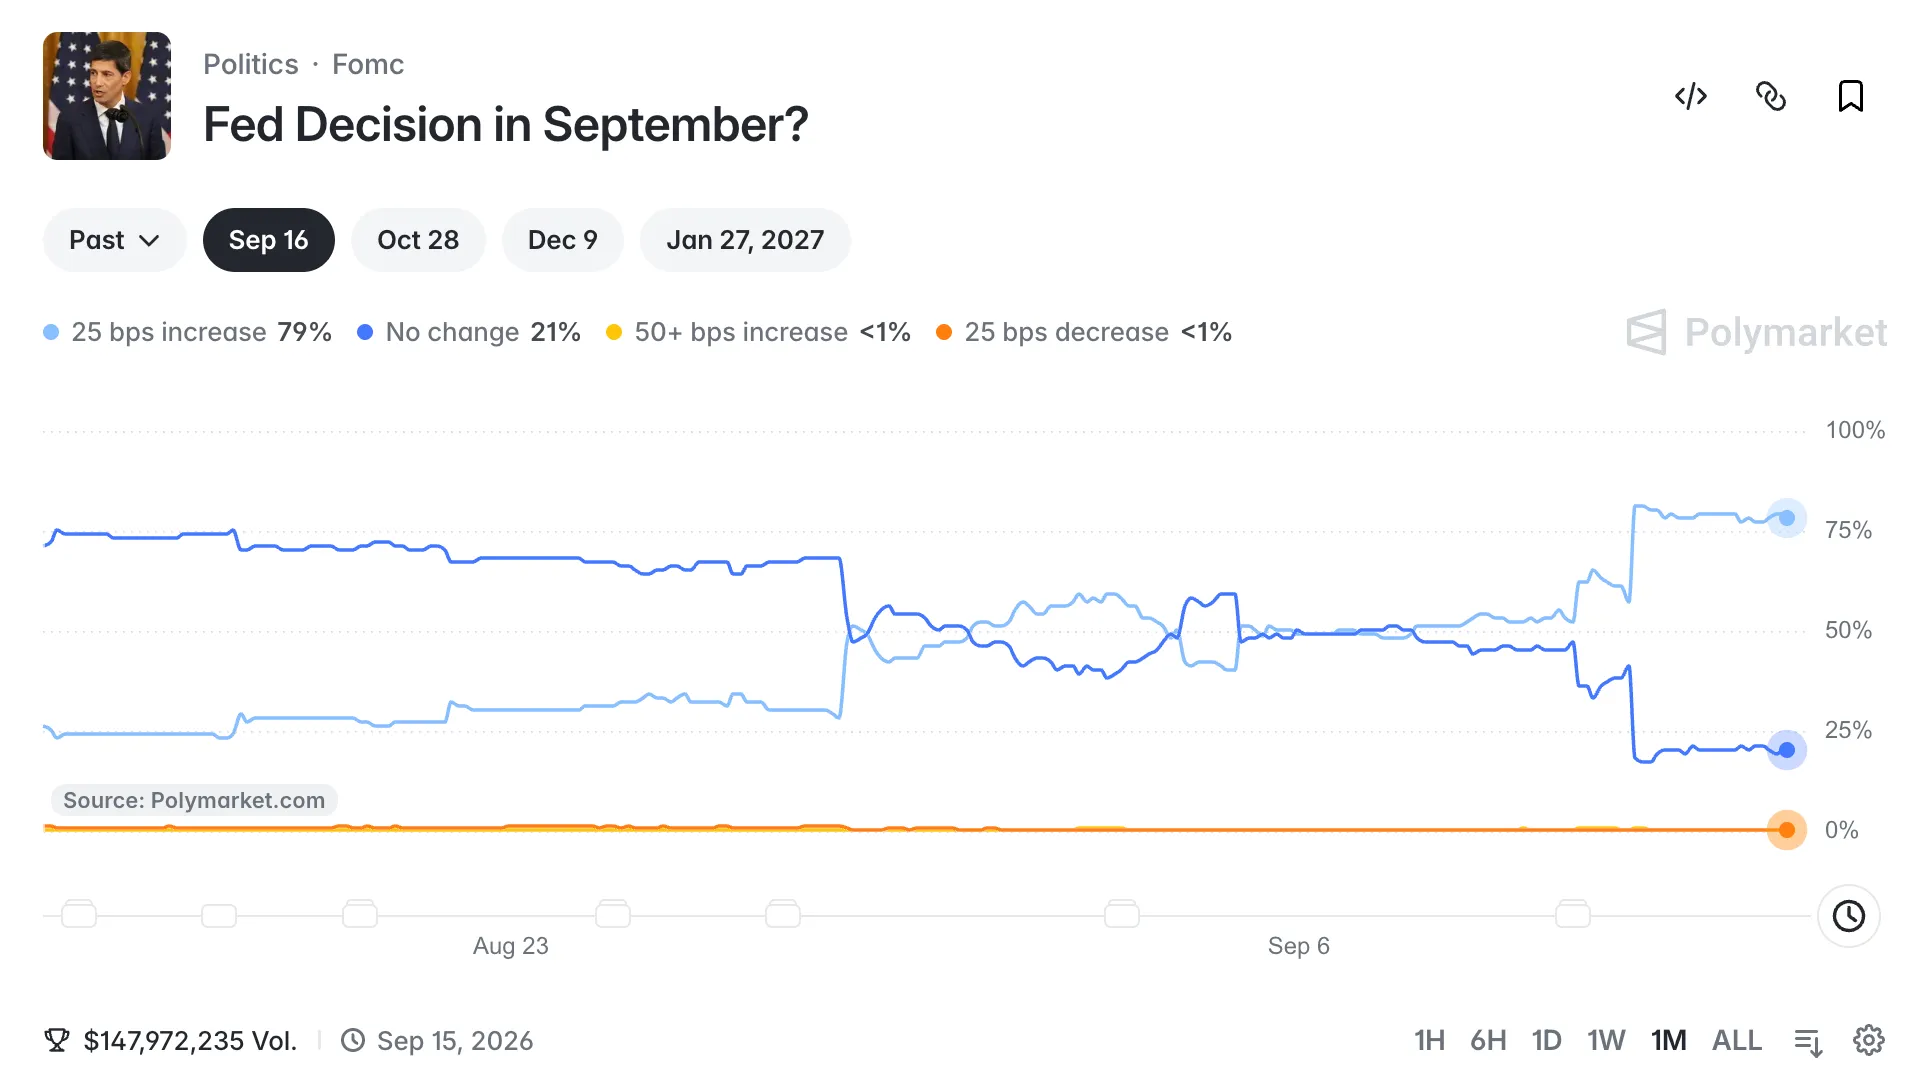
Our take is that a 25bp hike is not a significant number at a current rate of 3.50% to 3.75%. What matters is the expectation of where rates go from here, whether more hikes follow and by how much. Assets re-rate on deviations from what is expected, not on what is already priced in.
CLARITY Jumps on Final Draft
Polymarket priced 2026 enactment at 16% on September 6 and 25% into the weekend, against 82% in February. Then Senate Republicans released what they called their last, best and final offer late Sunday night, settling the ethics fight that has blocked the bill since January. Officials and their spouses would have to divest crypto holdings or use a blind trust, with state attorneys general enforcing. Trump agreed to it. Odds of the CLARITY Act passing into law this year rose 13 points to 33% on the news.
Volatility, Positioning and Leverage
BVIV opened the week at 40.64, ran to 42.24 on September 10, then fell to 38.86 during the CPI session and closed the week at 40.51. A textbook event crush: the uncertainty spiked before the big event (CPI print) and dips once markets absorb the numbers.
Aggregate futures open interest is $133.4B against $139.7B last issue, down 4.5%. Both sides got caught by the PPI and CPI induced volatility, with $685.6M in liquidations on September 11, split $385M short and $300M long. Coinglass's aggregate 24-hour long/short ratio is 49.71% / 50.29%, essentially neutral going into this week of decisions.
ETF Flows Reverse
BTC and ETH ETFs took $265.6M of net outflows combined, ending three consecutive weeks above $1B.
BTC: -$462.7M. Four straight outflow sessions and no inflow days. Cumulative flows since launch stand at $55.15B. Year to date is back to -$1.46B, against -$0.90B last issue. The flows line up with investors de-risking ahead of a volatile week.
ETH: +$197.1M. On Friday, ETH drew $216.4M while BTC lost $13.3M. Cumulative flows are $13.39B, AUM $16.31B, and year to date sits at +$1.06B. ETH held up against BTC through the uncertainty, which bodes well for how it trades once the market digests the regulatory and macro decisions ahead.
Key Events for the Week Ahead
Tuesday, September 15
- CLARITY Act cloture vote on the motion to proceed, 2:15pm ET. Needs 60.
- FOMC convenes, day one.
Wednesday, September 16
- FOMC decision, 2pm ET, with the Summary of Economic Projections and dot plot. Warsh press conference at 2:30pm ET.
- US August retail sales, 8:30am ET.
Thursday, September 17
- Bank of England rate decision.
- Bank of Japan meeting, decision due Friday.
- US initial jobless claims and the Philadelphia Fed index.
Friday, September 18
- Quadruple witching. Large equity index and single-stock expiry, usually a volume and volatility event.