Eyes on the Market: Shrugging Off Bad News
Published On 21 September 2026
- Crypto faced two bad headlines and closed up anyway. BTC rose 5.53% to $81,091, ETH 6.35% to $2,634 and total market cap 6.03% to $2.777T. HYPE hit an all-time high of $94.23 and SOL added 11.5% to a seven-month high.
- Missing CLARITY. Cloture failed 49 to 50, eleven short of the 60 needed. Every Democrat who voted opposed it, along with four Republicans. The next realistic window is a lame-duck session or 2027.
- The agencies moved without Congres. The SEC's Innovation Exemption gave tokenized securities venues five years of relief from the exchange definition, and the CFTC shielded passive software providers the same day. Arbitrum gained 55% on the week, Securitize and Uniswap 37%.
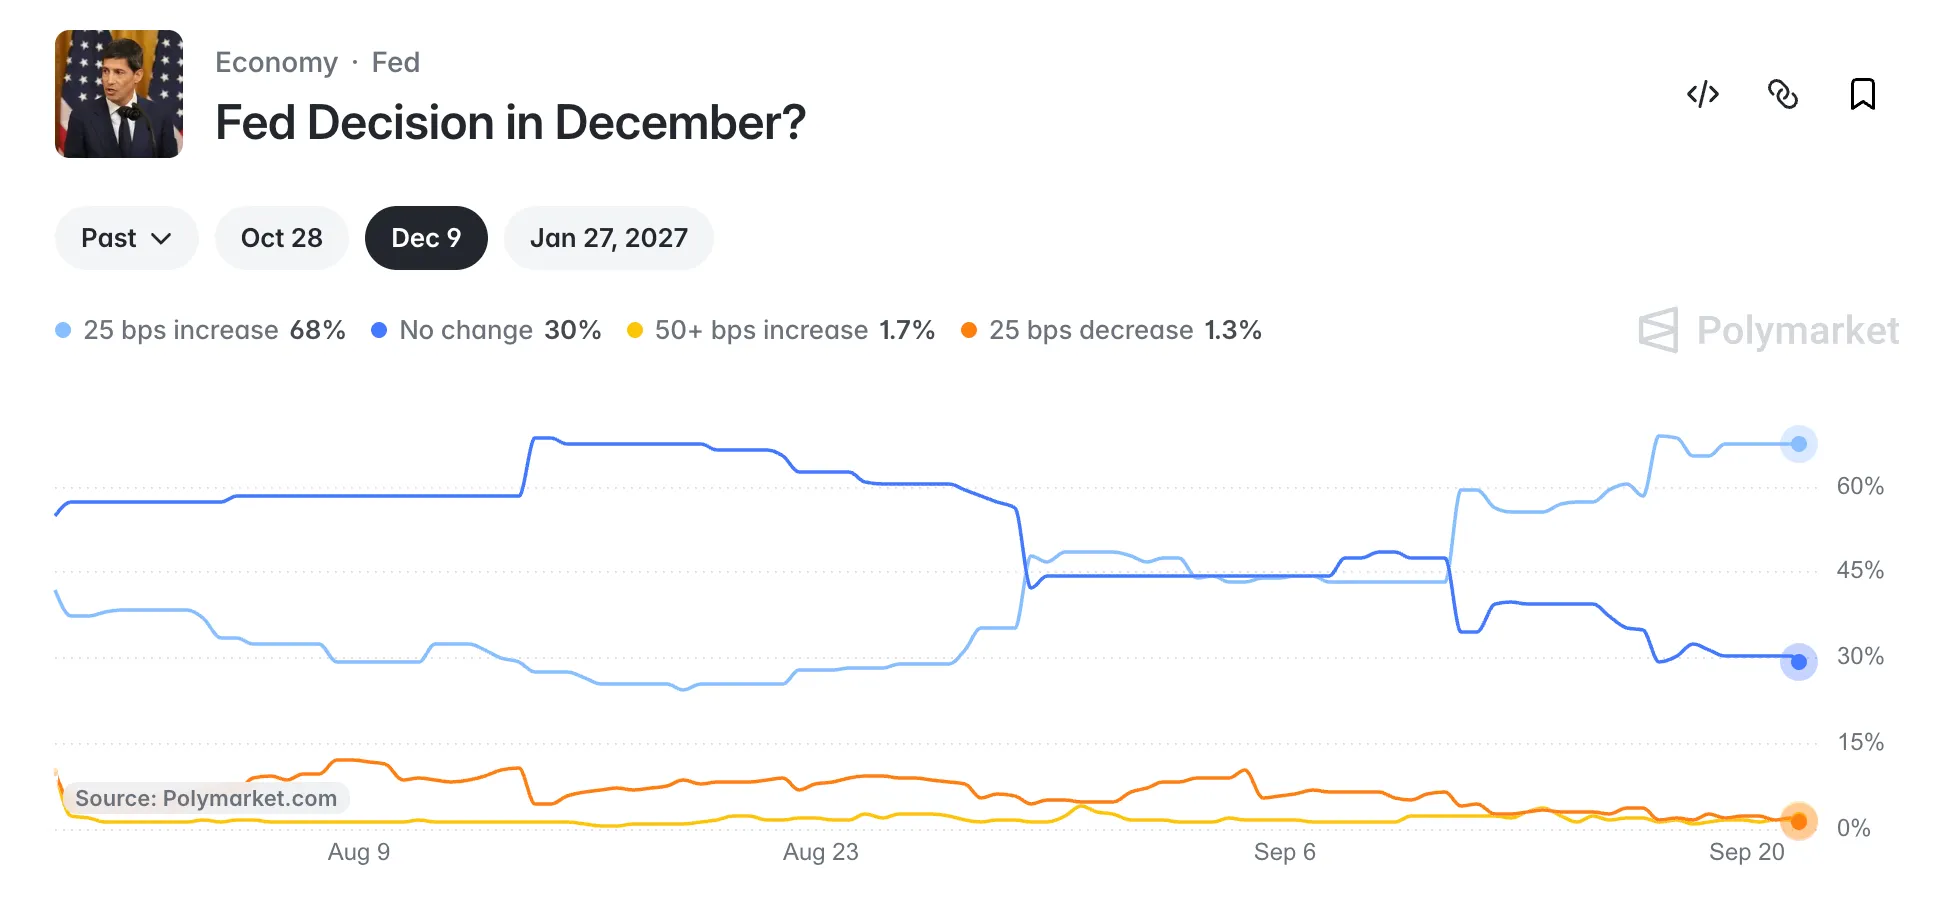
- The Fed hiked 25bp to 3.75% to 4.00%, unanimously, its first increase since July 2023. Of the 18 dots submitted, 16 see another hike this year and four see two. Polymarket prices 55% for October 28 and 68% for December 9.
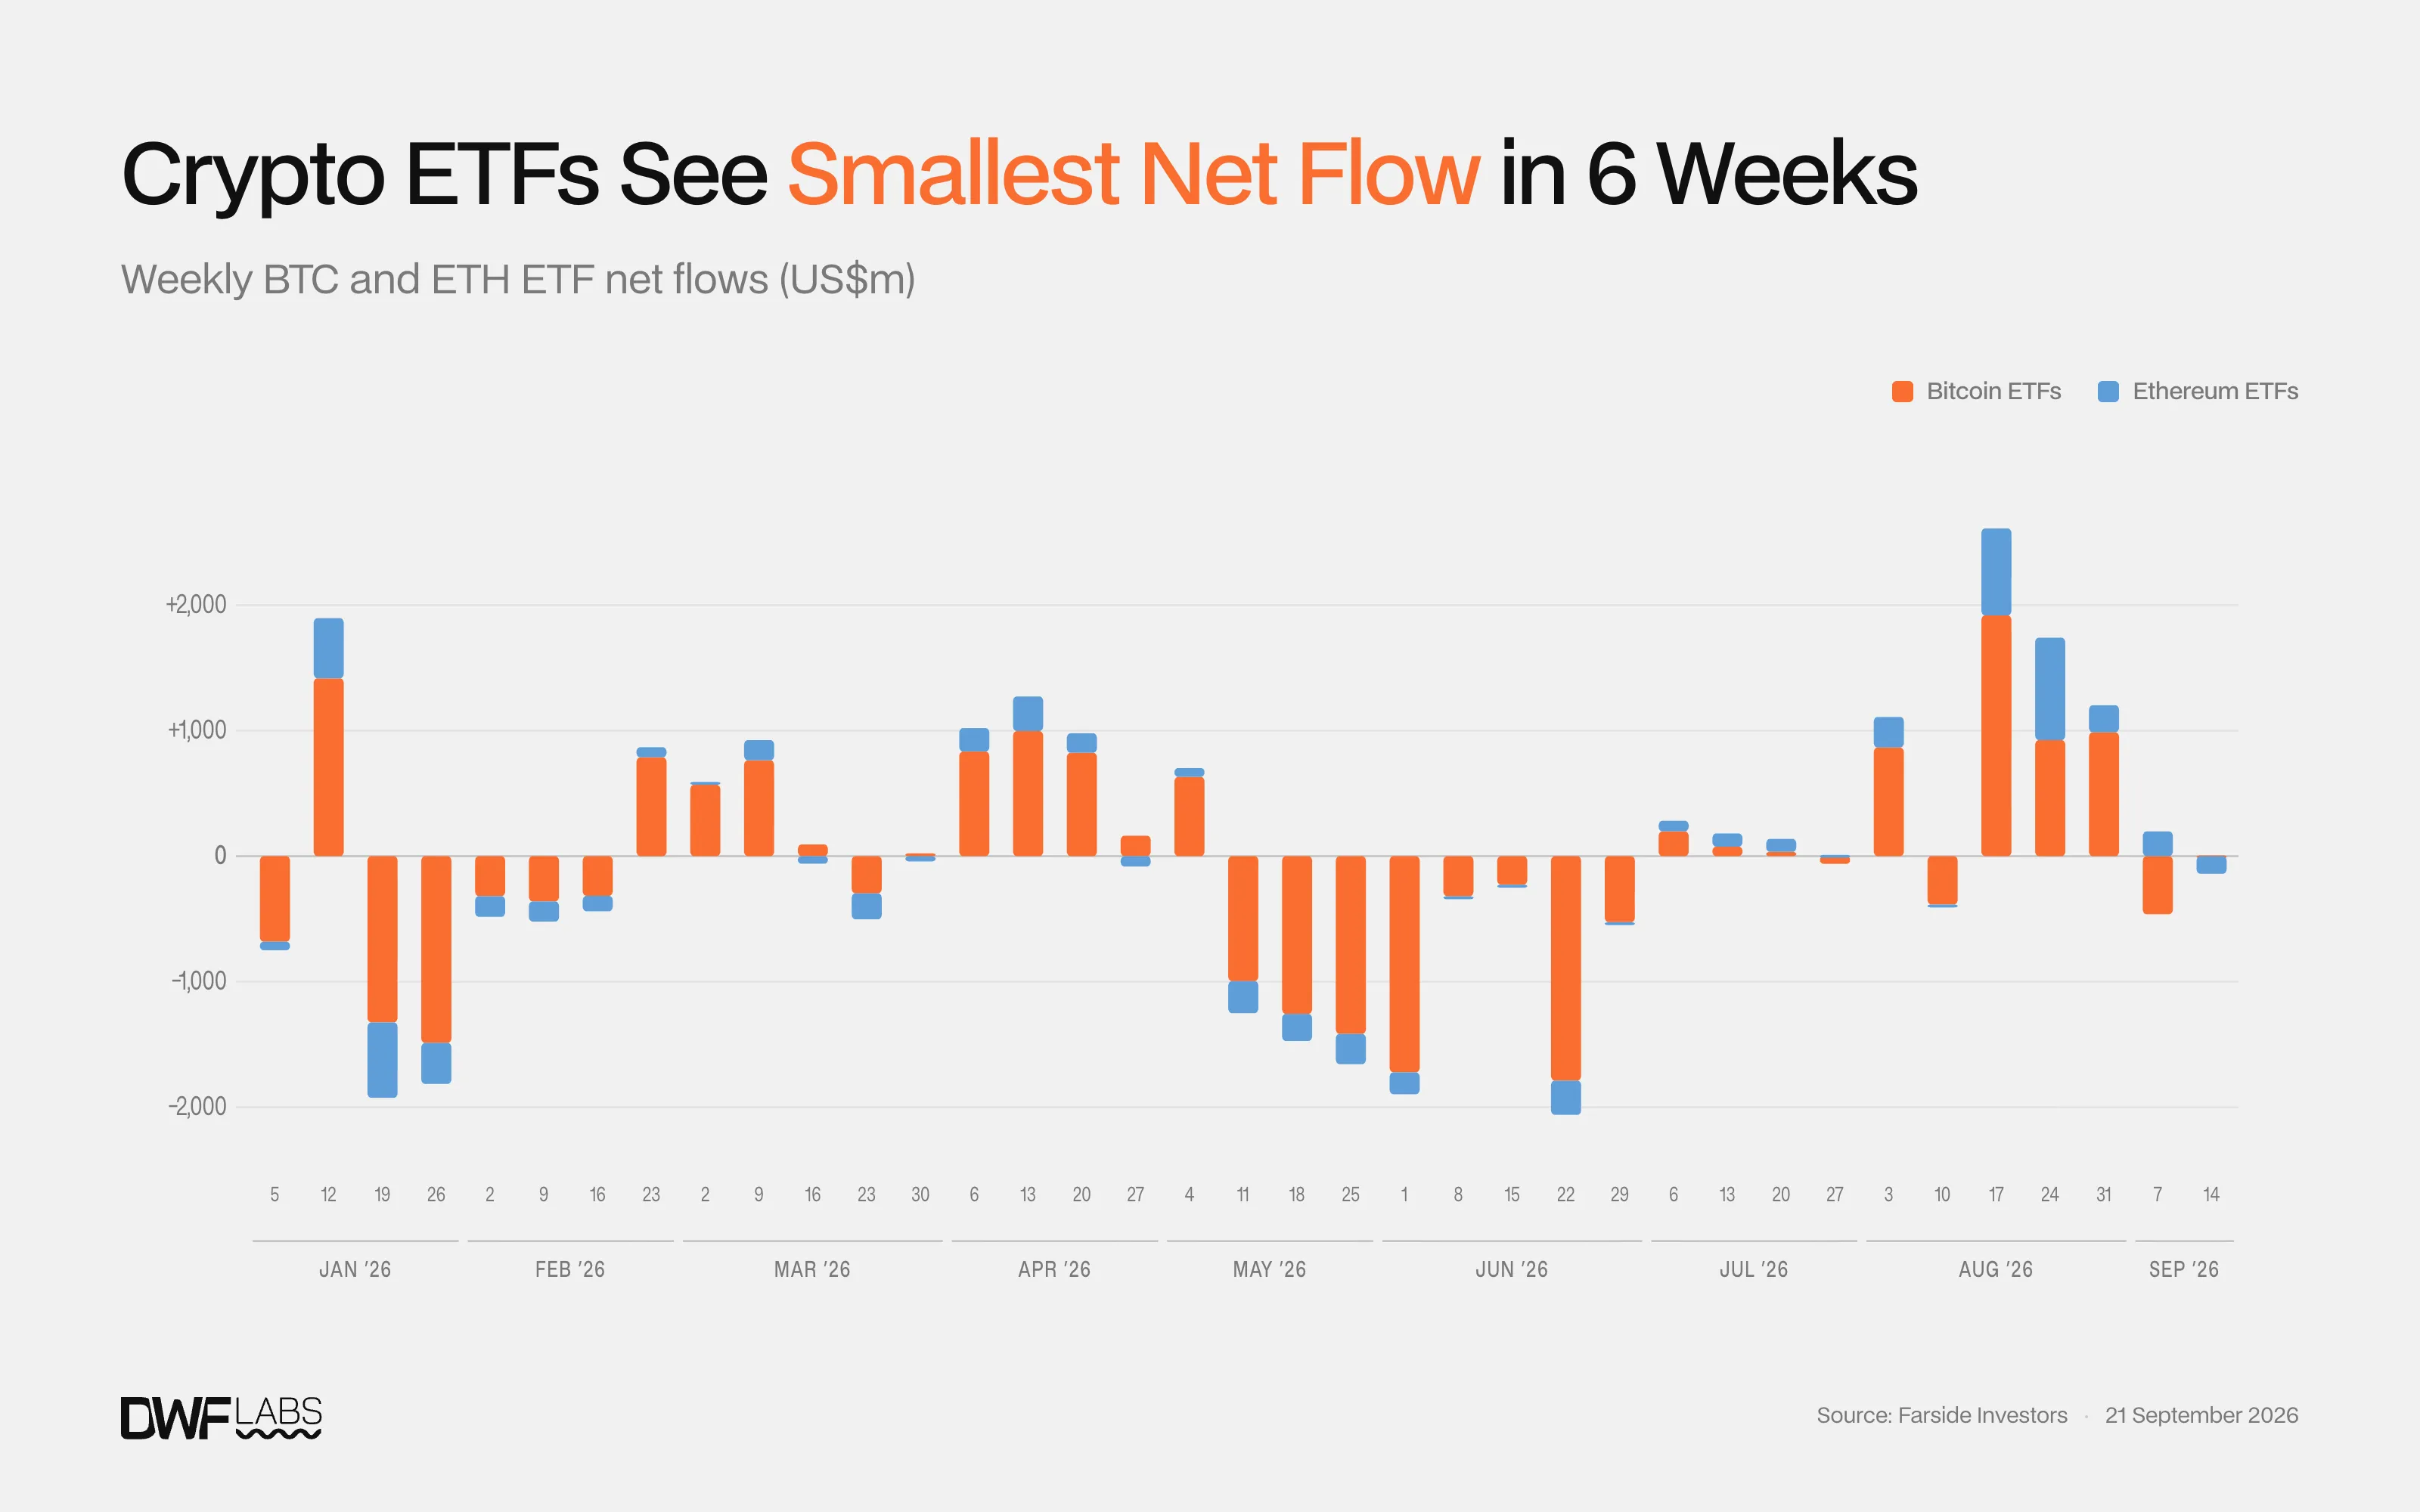
- BTC ETFs netted $6.1M, the smallest week since launch in January 2024. ETH lost $140.6M, its worst week since June 22.
Prices rebound after FOMC
BTC opened Monday at $76,842, closed Tuesday at $75,935 on the CLARITY cloture rejection, and continued to slide down to $75,383 ahead of FOMC. It gained 6.14% on Friday alone and closed Sunday at $81,091, up 5.53% on the week.
ETH ran further, from $2,477 to $2,634, up 6.35%, with the same Wednesday low of $2,398. Total crypto market cap gained 6.03% to $2.777T. HYPE hit an all-time high of $94.23 on Friday against a prior high of $89.57. SOL added 11.5% to a seven-month high.
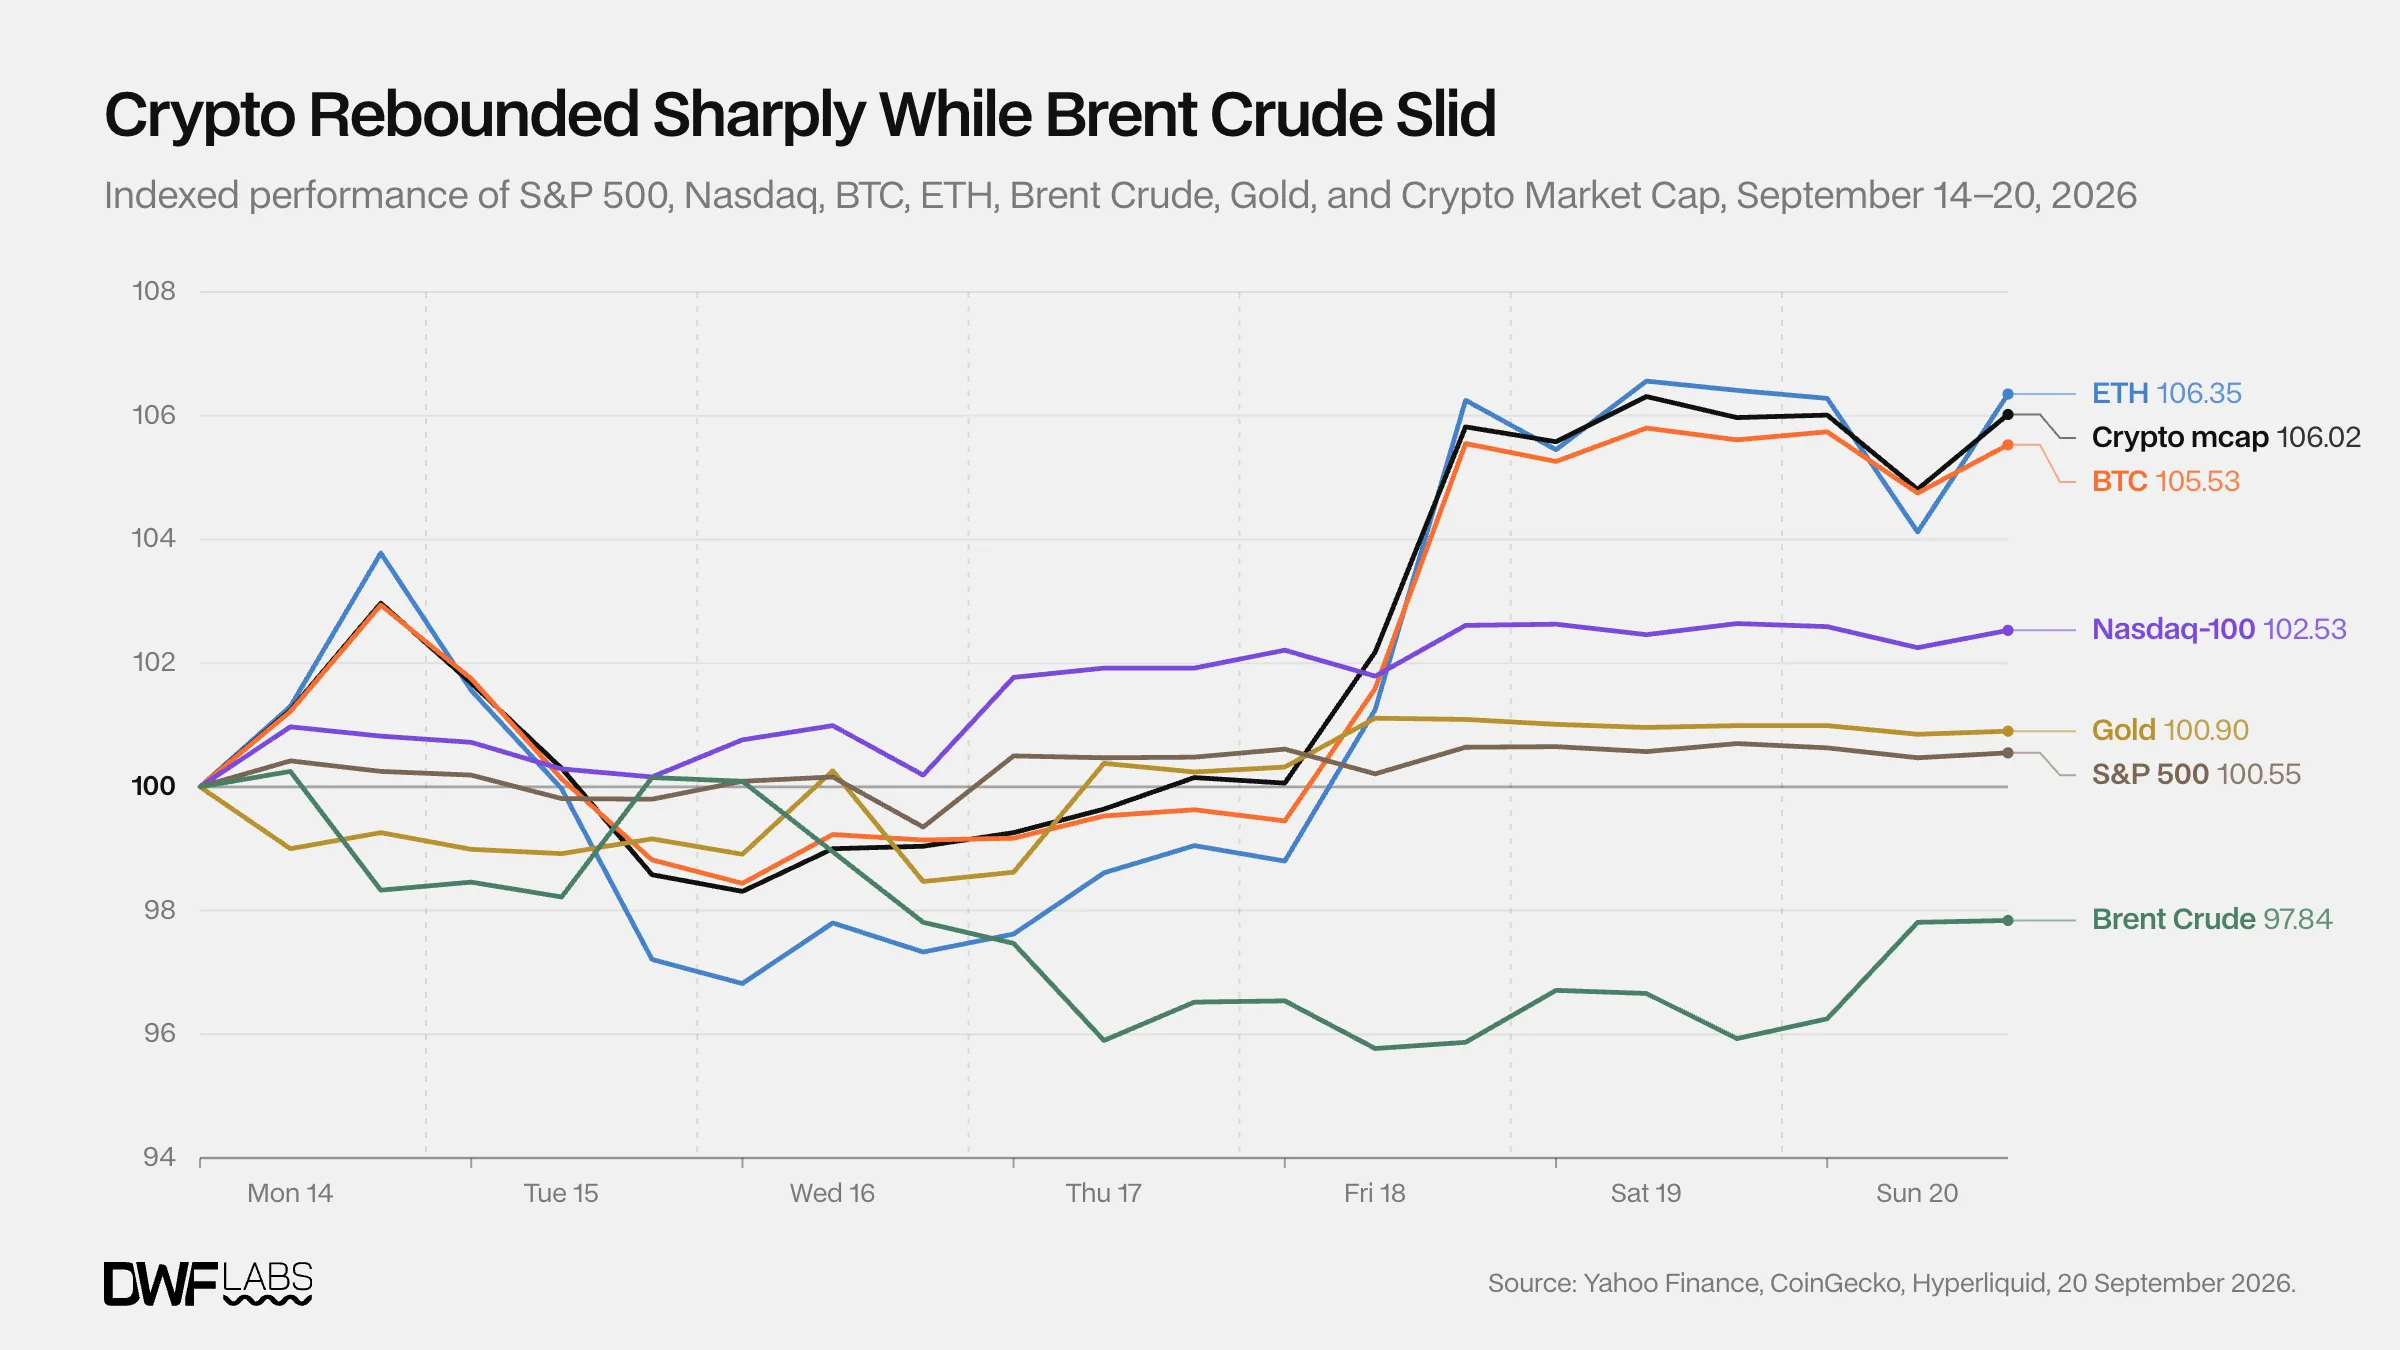
Equities saw a similar trend. On Wednesday the Dow lost 1.21% to 51,461, the S&P 500 0.45% to 7,551 and the Nasdaq-100 closed flat at 28,945, all three having been higher before FOMC. Thursday reversed most of it, with the Nasdaq 100 up 1.73% to 29,447 and the S&P 1.1%.
Brent fell 2.16% to $100.75 as supply concerns eased. Saudi Arabia loaded more crude via Oman, product inventories built in the United States, Singapore and Europe, and China raised fuel exports.
What happened during the week
CLARITY fails its cloture vote
On September 15 the Senate voted on cloture for the CLARITY Act. Sixty votes were needed to end debate on the motion to proceed and open the bill to floor consideration. It failed 49 to 50, eleven short. Every Democrat who voted opposed it, including the seven who negotiated the text and the ethics rewrite, and four Republicans joined them. Senators leave Washington in early October and do not return until after the November 3 midterms, so the realistic window now is a lame-duck session or 2027.
Fed hikes
The FOMC raised the target range 25bp to 3.75% to 4.00% on Wednesday, September 16, a 12-0 vote and the first increase since July 2023. Warsh said inflation has been too high for too long and pointed to too many categories running above 3% on both six and twelve-month horizons. The 2-year yield rose to roughly 4.73% and the 10-year held near 5.00%.
The Fed’s dot plot revealed their projections. Of the 18 participants who submitted, 16 see at least one more hike this year and four see two. None sees a cut or a hold below the new range. Polymarket prices a 55% chance of a 25bp hike on October 28 and 68% on December 9.
The SEC and CFTC moves without Congress
On Thursday, September 17, the SEC issued the Innovation Exemption. It grants two forms of temporary conditional relief. Tokenized Securities Venues are exempt from the definition of "exchange" for five years, letting them run secondary trading in tokenized NMS stocks through permissioned automated market makers. Liquidity providers supplying proprietary capital to those pools are exempt from dealer registration. Venues that believe they qualify need only notify the Commission before starting. The order is effective immediately and open for comment, with durable rule-making to follow.
The same day, the CFTC's Market Participants Division issued a no-action position shielding passive non-custodial software providers from introducing broker and associated person registration.
Both agencies moved inside 48 hours of the failed vote, signaling their desire for crypto regulatory clarity with or without Congress. Over the past week Arbitrum gained 55%, Securitize 37%, Uniswap 37% and Ondo 20%.
Two more central bank meetings
The BoE held Bank Rate at 3.75% on Thursday, a sixth straight hold, 6-3 with Pill, Greene and Mann voting for 4.00%. UK CPI hit 3.1% in August. Given hawkish pricing going in, the hold weakened sterling.
The BoJ hiked 25bp to 1.25% on Friday, 7-2, its highest policy rate since 1995 and its sixth increase of a cycle that started at minus 0.1% in March 2024. It came three months after the last hike, against a prior cadence closer to one every six months. The yen weakened past 157 and the Nikkei gained 1.5%: the market read the split vote and the absence of updated forecasts as evidence the BoJ is not set up for back-to-back moves.
Volatility, positioning and leverage
BVIV sits at 37.44 against 40.51 at last issue's close, down 7.6% through the single most event-dense week of the quarter. It is now below the 38.86 low printed during the August CPI session and within two points of the August 7 low of 35.81. Two rate decisions, a failed market-structure vote and a regulatory reversal produced a lower implied vol than the week before them.
Aggregate futures open interest is $148.2B against $133.4B last issue, up 11.1%, and the highest reading since January. BTC-denominated open interest has recovered from its September 13 low of 658.6K BTC to 690.2K, but that still sits below every daily reading since April.
ETF flows fall flat
BTC and ETH ETFs took $134.5M of net outflows combined, a second consecutive negative week and the smallest combined net flow in either direction in six weeks.
BTC: +$6.1M. The smallest weekly net since BTC ETFs launched in January 2024. Do not mistake a small net for a quiet week. Daily prints ran from -$450.4M to +$433.0M, with nearly $1.5B moving in both directions across the five sessions to land on $6.1M. Tuesday's $450.4M outflow is the largest single day since June 25, and Friday's $433.0M erased most of it as BTC crossed $80K.
ETH: -$140.6M. This is ETH's worst week since June 22. It also ends a four-week run of $1.94B of inflows. Despite seeing outflows, ETH still outperformed BTC from a price action standpoint.
The best performer of the week was Solana. Its ETFs saw $58.7M of net inflows. Cumulative flows across the six funds total $1,274.6M excluding $449.3M of seed capital. BSOL alone accounts for $1,090.1M, 86% of the category.
Key events for the week ahead
Monday, September 21
- China: PBoC one-year and five-year Loan Prime Rate fixings, expected unchanged at 3.00% and 3.50% for a sixteenth month.
- US: Chicago Fed National Activity Index for August.
Tuesday, September 22
- US: Weekly ADP Employment Change data
Wednesday, September 23
- Global: S&P Global flash manufacturing, services and composite PMIs, US release 9:45am ET.
Thursday, September 24
- US: initial jobless claims, 8:30am ET. New home sales, 10am ET.
- Australia: August labour force report.
Friday, September 25
- US: advance durable goods for August, 8:30am ET.